WhatsApp Has a New Boss. Your Group Chats Might Never Be the Same.
Who is Kunal Shah and why does Meta want him?
Kunal Shah is not a messaging guy. He's a payments guy — specifically, a payments guy who figured out how to convince India's wealthiest credit card users to pay for a premium financial membership. His company, CRED, is an invite-only platform for people with high credit scores who pay their bills on time. It offers rewards, exclusive deals, and a sense of belonging to a financial elite. It has never tried to serve the mass market.
That's exactly what makes this appointment so fascinating — and so risky. WhatsApp's 500 million users in India are the opposite of CRED's base. They're farmers in Maharashtra, small shop owners in Uttar Pradesh, students in Kolkata, families sending remittances between cities. They use WhatsApp because it's free, it's simple, and everyone they know is already on it. Shah has built his career serving the top 1% of Indian consumers. Now Meta is asking him to build for everyone else.
India's payment battlefield — and why WhatsApp is losing
To understand why Meta is willing to spend $9 billion and risk a leadership shakeup, you need to look at India's digital payments market. It is, by any measure, one of the most competitive in the world — and WhatsApp is barely in the game.
PhonePe, backed by Walmart, controls roughly 46% of the market with over 500 million users. Google Pay holds about 33% with 300 million users. Together, these two process the vast majority of India's digital transactions. The former market leader, Paytm, has collapsed to just 8% after regulatory troubles. WhatsApp Pay, despite launching with enormous fanfare in 2020, sits at less than 1%.
The problem isn't technology — WhatsApp Pay works fine. The problem is habit. Indians already have PhonePe and Google Pay on their phones, linked to their bank accounts, integrated into every street vendor's QR code. Switching to WhatsApp Pay means adding yet another payment method to a life that already has two working ones. It's a behavior change problem, not a product problem.
What this means for you: the WhatsApp you'll see in 2— years
For the average WhatsApp user — whether you're in Mumbai, Manila, or Manchester — the changes won't happen overnight. But the direction is clear. Here's what to expect:
More businesses will reach you through WhatsApp. Over a million companies already use Meta's business messaging tools across WhatsApp and Messenger, mostly for basic customer service. Under Shah, expect that number to grow sharply — and expect those interactions to become more sophisticated. Instead of calling a bank's hotline and waiting on hold, you'll message them on WhatsApp and an AI agent will handle your request. Instead of receiving a shipping update via SMS, you'll get it in a WhatsApp chat with the retailer.
Paying people inside group chats. The most WeChat-like feature on the horizon: splitting a dinner bill, collecting money for a group gift, or paying your share of the rent — all inside the group chat where you're already having the conversation. No third-party payment app. No "please send me your UPI ID." Just tap, pay, done.
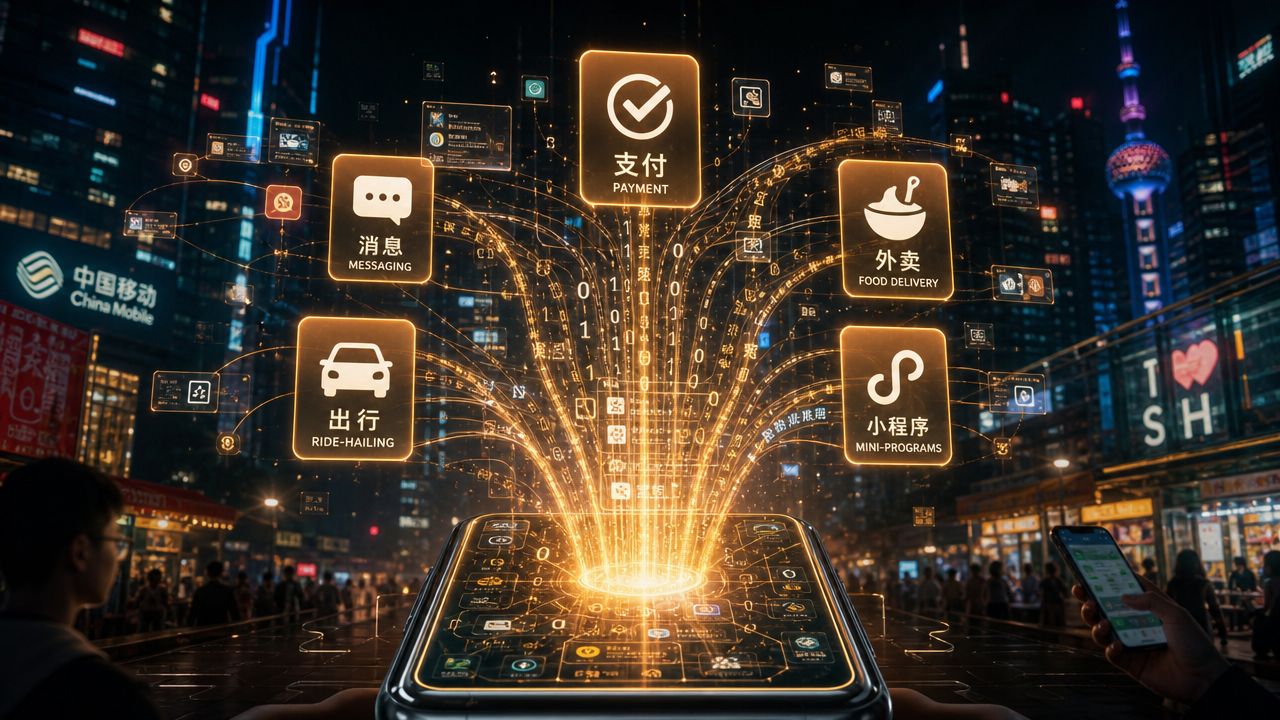
Mini-apps that live inside WhatsApp. WeChat's killer feature is its ecosystem of "mini-programs" — lightweight apps that run inside the messaging app. You can order a taxi, book a doctor's appointment, pay your electricity bill, or play a game without ever installing anything new. Meta has been building the infrastructure for this on WhatsApp for years. Under Shah, expect the pace to accelerate.
The China comparison that everyone is making — and why it matters
Tech analysts love to compare every messaging app to WeChat, and for good reason. WeChat is the closest thing the world has to a true everything-app: 1.3 billion users, a payments ecosystem that processes trillions of dollars annually, and a mini-program economy so embedded in Chinese daily life that people genuinely struggle to function without it. It is, in many ways, the internet in China.
But WeChat grew up in a unique environment — one where Google, Facebook, and most Western platforms were blocked, leaving a vacuum that Tencent filled. WhatsApp doesn't have that advantage. In India, it competes with PhonePe and Google Pay. In Brazil, it competes with Pix. In Southeast Asia, it competes with Grab and Shopee. Building a WeChat outside of China means building it in markets where other super-apps already exist — and are profitable.
Shah's bet is that WhatsApp's 3-billion-user installed base is an advantage no competitor can match. You don't need to convince people to download a new app. You just need to convince them to use the app they already open 20 times a day for more things.
What this hire says about Meta's real strategy
Meta didn't promote a WhatsApp veteran or poach a Google Pay executive. They hired a fintech founder — someone who built CRED by obsessing over India's most affluent 1%, designing every interaction for people who already have five credit cards and a finance app for each one. Now they're asking that same person to build for the 500 million Indians who have never made a card payment in their lives.
That choice tells you more about Meta's strategy than any press release could. First: WhatsApp's internal culture cannot produce a WeChat. If it could, it would have by now. The app has been building payments infrastructure for five years and still sits at less than 1% market share. Promoting from within would signal continuity; hiring Shah signals a clean break — new leadership, new playbook, new urgency. Second: this is a payments problem, not a messaging problem. WhatsApp doesn't need better chat features. It needs a transaction layer that works for people who think about money differently than Silicon Valley product managers do. Shah's entire career has been about getting Indians to trust digital money — first at FreeCharge, then at CRED. That is the muscle Meta is buying, not his ability to ship app updates.
The tension at the heart of this hire — and the reason it will either work spectacularly or fail quietly — is that CRED and WhatsApp Pay are opposites in almost every way that matters. CRED was exclusive. WhatsApp Pay needs to be universal. CRED made money from people who already had money. WhatsApp Pay needs to make money from people who have almost none. CRED succeeded by making finance feel premium. WhatsApp Pay needs to succeed by making finance feel invisible.
The name on your WhatsApp screen won't change. The green icon will stay green. But the app itself is about to go through the biggest transformation since Facebook bought it for $19 billion in 2014. Whether that transformation makes your life easier or more cluttered depends almost entirely on whether Kunal Shah can figure out how to build for 500 million people the same way he built for a few hundred thousand.